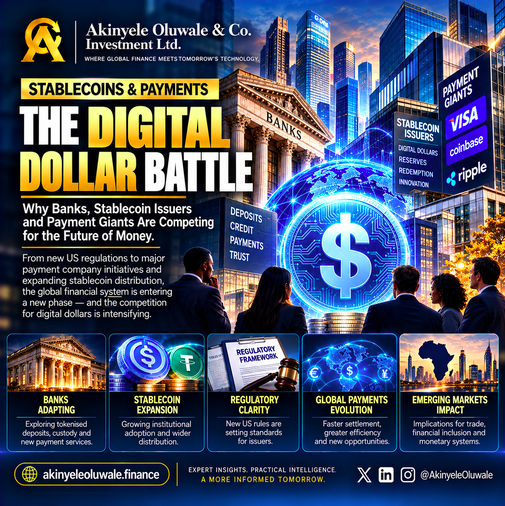
As regulated stablecoins gain institutional attention, the competition is no longer simply about cryptocurrency. It is about who issues digital money, who controls payment infrastructure, and who earns the economic value created when money moves.
Published: October 29, 2026 | Category: Stablecoins & Payments | By: Akinyele Oluwale
Something important is happening in the global financial system. For decades, commercial banks have played a central role in holding customer deposits, facilitating payments and supplying credit to households and businesses. Payment networks have connected merchants, consumers and financial institutions.
Central banks have maintained monetary frameworks and provided the foundations for settlement in sovereign currencies.
Now, stablecoin issuers are introducing another way to represent and transfer monetary value.
These issuers create digital tokens designed to maintain a stable value relative to a reference asset, most commonly the US dollar.
Unlike Bitcoin, whose market price can fluctuate significantly, a dollar-backed payment stablecoin is generally intended to maintain a value close to one US dollar.
However, the fact that a token targets a stable price does not make it identical to cash or a bank deposit.
Its reliability depends on the issuer, the assets supporting it, redemption arrangements, legal rights and operational controls.
The growing interest in stablecoins from payment companies, financial institutions and regulators is therefore more than a technological development.
It raises a strategic question about the organisation of the financial system.
If digital dollars can move across blockchain networks, what role will traditional banks play in issuing money, safeguarding customer funds and facilitating payments?
The answer will not necessarily involve one industry replacing another.
Instead, competition and cooperation may develop between banks, stablecoin issuers, payment networks and technology providers.
The institutions that successfully combine trust, regulatory compliance, customer access and efficient settlement may play an increasingly important role in the next generation of financial services.
Let us begin with a simple example.
Suppose a business maintains $100,000 in a commercial bank account. That balance represents a claim against the bank, subject to the applicable account terms, banking regulations and deposit-protection arrangements.
The bank may use deposits as part of its funding base while managing liquidity, capital requirements and other financial obligations.
Now imagine that the business converts part of its balance into dollar-backed stablecoins.
Instead of holding the entire amount as a bank deposit, the business now holds digital tokens whose value and redemption depend on the stablecoin arrangement.
The economic relationship has changed. The company may gain access to different payment capabilities, but it also assumes a different combination of issuer, custody, technology and legal risks.
This distinction is essential.
A stablecoin is not automatically a safer or more profitable substitute for a bank account. Nor is every bank deposit equally suitable for international payment settlement.
Different instruments serve different purposes.
For business leaders, the issue is whether stablecoins can provide meaningful improvements in payment efficiency without creating unacceptable financial risks.
For banks, the issue is whether new digital-money products could change customer behaviour, deposit funding and payment-service revenues.
For regulators, the challenge is to encourage useful innovation while protecting consumers, financial stability and the integrity of the monetary system.
For emerging economies, the questions extend to foreign-exchange markets, monetary sovereignty and the growing use of foreign-currency instruments.
Stablecoins therefore deserve attention not because they are fashionable, but because they could influence how financial claims are issued, transferred and redeemed.
Several developments provide context for this emerging competition.
In October 2026, the Office of the Comptroller of the Currency finalised an implementing framework under the GENIUS Act for payment stablecoin activities within its jurisdiction.
The framework addresses matters such as permitted activities, reserve management, redemption obligations, risk management and supervision.
Its scheduled effective date is January 18, 2027.
This matters because payment stablecoins intended for institutional use require more than market demand.
They require clearly defined legal obligations and supervisory expectations.
A financial institution considering stablecoin services needs to understand who may issue the instrument, what assets must support it and what happens when a holder requests redemption.
Regulatory clarity does not eliminate financial risk.
However, it can establish standards against which market participants are assessed.
Visa's October announcement that stablecoin-enabled prefunding through Visa Direct had moved into commercial deployment is another important development.
The initiative initially involves eligible partners and payment-service arrangements rather than a universal change to the Visa network.
Its significance is strategic.
Established payment companies are exploring how blockchain-based instruments might support the movement of funds within existing payment operations.
This creates opportunities for cooperation between traditional financial infrastructure and digital-money providers.
It also raises questions about which institutions will provide settlement liquidity, custody and related services.
Coinbase's October 28 expansion of access to Ripple's RLUSD stablecoin highlights another dimension of the market.
Stablecoin issuers need reliable distribution and liquidity channels.
Digital-asset platforms can help connect issuers with users, institutions and potential payment applications.
However, increased distribution does not automatically establish that a stablecoin is being widely used for commercial payments.
A token's availability, transaction volume and real-world payment adoption are separate measures.
This distinction is important when assessing industry announcements.
The question is not simply how many platforms support a stablecoin.
It is whether businesses and financial institutions are using it to solve identifiable payment problems.
To understand the competition, we must first understand what customers actually hold.
Money in a commercial bank account generally represents a deposit liability of that bank.
A privately issued stablecoin represents a different claim or contractual arrangement, depending on its legal structure.
Both may be denominated in dollars, but their legal rights, protections and operational characteristics can differ.
A bank deposit may be covered by deposit insurance within applicable limits and jurisdictions.
A payment stablecoin should not be assumed to enjoy equivalent protection.
Similarly, a stablecoin's reserve assets may include high-quality liquid instruments, but the existence of reserves does not automatically guarantee uninterrupted redemption under every possible circumstance.
The quality of reserve management, custody arrangements and legal enforceability matters.
Banks have several reasons to monitor stablecoin developments.
First, payment services are an important part of customer relationships.
If businesses increasingly use alternative networks for certain transfers, banks may need to adapt their payment offerings.
Second, customer deposits are an important source of bank funding.
If substantial balances move from deposits into privately issued digital-dollar instruments, the consequences could affect funding arrangements.
However, the net effect on the banking system depends on where stablecoin reserves are held and how funds circulate.
Money moving out of one customer's deposit account does not necessarily disappear from the banking system.
Third, banks may see commercial opportunities in providing custody, reserve banking, settlement and other regulated services.
The relationship between banks and stablecoin issuers may therefore involve competition in some areas and cooperation in others.
There is another issue that receives less attention.
Stablecoin issuers may earn income from eligible assets held as reserves, depending on their business models and applicable regulations.
Payment providers may earn fees from transaction processing or associated services.
Banks may provide custody, liquidity and account services.
Technology providers may earn revenue from infrastructure.
These economic incentives help explain why so many institutions are interested in digital-money infrastructure.
The opportunity is not limited to creating a token.
It includes providing the services that make the token useful.
For institutional investors and business leaders, understanding these revenue models is important when evaluating the long-term sustainability of the industry.
Most widely discussed payment stablecoins are denominated in US dollars.
That creates an additional dimension for countries outside the United States.
A business using dollar stablecoins may gain access to a dollar-denominated payment instrument.
But widespread use of foreign-currency digital instruments could also raise questions about domestic currency demand, capital flows and monetary-policy effectiveness.
The implications will differ across countries.
A stablecoin that supports international trade settlement may provide useful services.
At the same time, regulators must consider how such instruments interact with foreign-exchange rules, anti-money-laundering obligations and domestic financial stability.
For Nigeria, this is an area requiring careful economic and regulatory analysis rather than simplistic claims that digital dollars will solve every cross-border payment challenge.
The emerging digital-dollar competition could influence several parts of the financial system.
Commercial banks: Banks may develop tokenised deposit products, offer services to stablecoin issuers or integrate blockchain-based settlement into existing operations. They may also face competition for certain payment activities.
Payment networks: Companies with established customer relationships and regulatory infrastructure may explore how stablecoins can improve settlement and liquidity management without abandoning existing payment systems.
Stablecoin issuers: Competition may increasingly depend on regulatory status, reserve quality, redemption reliability, institutional partnerships and genuine transaction demand.
Corporate treasury departments: Businesses may evaluate whether stablecoin arrangements offer advantages for international payments, particularly where operating hours and settlement delays create practical challenges.
Government debt markets: Reserve-backed stablecoins may create demand for eligible short-term government instruments. The scale of any broader market impact will depend on the size of the industry and the composition of reserves.
Emerging economies: Policymakers may need to assess the relationship between foreign-currency stablecoin usage, domestic payment systems and monetary conditions.
Digital-asset markets: Stablecoins can support liquidity and settlement across blockchain networks, but their wider adoption does not guarantee higher prices for speculative cryptoassets.
The common theme is that digital money affects financial intermediation, not merely transaction technology.
The debate about stablecoins is frequently presented as a contest between old finance and new finance.
That description is too simplistic.
Traditional financial institutions possess capabilities that remain important: regulatory oversight, customer identification, credit assessment, risk management and established legal relationships.
Blockchain-based systems offer different capabilities, including programmable transfers and the potential for settlement outside conventional operating hours.
The most useful question is how these capabilities can be combined responsibly.
A payment system should be judged by what it delivers to users.
Does it reduce the total cost of completing a transaction?
Does it improve reliability?
Are customer rights clearly defined?
Can funds be redeemed under stressed conditions?
Who is accountable when something goes wrong?
These questions are more important than whether a payment travels through a blockchain or a traditional financial network.
For corporate executives, stablecoin adoption should be approached as a financial-management decision.
Management should assess the full transaction process, including currency conversion, custody, compliance, settlement and final receipt of funds.
A transfer that appears inexpensive on a blockchain may still involve significant costs elsewhere.
Likewise, a payment that settles quickly may not provide meaningful value if the recipient cannot access or convert the funds efficiently.
The correct measure of success is the complete business outcome.
The future of payments will not be decided by technology alone. It will be decided by trust, economics, regulation and the ability to solve real financial problems.
Seven developments deserve attention.
1. Regulatory implementation: The transition from published stablecoin rules to effective supervision will be important for institutional confidence.
2. Bank-issued digital-money products: Watch whether banks expand tokenised deposits and related settlement services.
3. Stablecoin redemption performance: The ability to redeem reliably, especially during periods of market stress, remains a fundamental measure of credibility.
4. Commercial payment adoption: Evidence of sustained business use will be more meaningful than announcements of technical integrations alone.
5. Reserve transparency: Investors and businesses should monitor disclosures about the assets supporting payment stablecoins and the arrangements protecting holders.
6. International regulatory coordination: Differences between national rules could influence where issuers operate and which payment services become available across borders.
7. African payment-system development: Regulators, banks and payment companies across Africa will need to evaluate how digital-dollar infrastructure interacts with domestic currencies, regional payment initiatives and financial inclusion.
These developments will help determine whether stablecoins become a lasting component of global finance or remain concentrated in narrower applications.
Stablecoins are introducing a new competitive dimension into digital payments and financial infrastructure.
Stablecoins and commercial bank deposits are different financial claims, even when both are denominated in US dollars.
Regulatory clarity is becoming increasingly important to institutional participation.
Banks may compete with stablecoin issuers in some areas while providing essential services to them in others.
Stablecoin business models extend beyond transaction processing to reserve management, custody, liquidity and infrastructure services.
Corporate adoption should depend on measurable efficiency, legal certainty and effective risk management.
Emerging economies must consider the implications of foreign-currency stablecoins for domestic monetary and financial systems.
The long-term winners will be determined by trust, utility, resilience and sustainable economics—not publicity.
Akinyele Oluwale & Co. Investment Ltd. is a financial intelligence platform focused on developments shaping institutional finance, digital assets, stablecoins, payments, tokenisation, central banking, artificial intelligence and global markets.
Our mission is to provide clear, evidence-based analysis that connects international financial developments with the practical decisions facing investors, business leaders and policymakers.
We believe financial intelligence should explain the forces behind market developments, identify relevant risks and support disciplined decision-making.
The competition for the future of digital money is becoming more serious.
Stablecoin issuers, commercial banks, payment networks and technology companies are exploring different ways to issue, safeguard and transfer monetary value.
Some will compete directly.
Others will form partnerships.
The eventual structure of the market may combine traditional banking capabilities with new settlement technologies.
But the fundamental responsibilities of finance will remain.
Money must be trustworthy.
Payments must be reliable.
Customer rights must be protected.
Financial institutions must remain accountable.
For business leaders and investors, understanding these principles is more important than predicting which company or technology will dominate.
The real question is not who creates the most digital tokens.
It is who can build a financial system that people and businesses can depend on.
Observe the change. Understand the implications. Position with discipline.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow's Technology.