The Market's New Dilemma: Weak Jobs, High Yields and the Battle Over Interest Rates
Published: October 4, 2026
Category: Macro & Global Markets
By: Akinyele Oluwale
The Market's New Dilemma: Weak Jobs, High Yields and the Battle Over Interest Rates: Why investors entering the new week must understand the growing conflict between slowing employment, inflation risk and expensive capital
The latest U.S. employment report delivered what would normally be considered a strong argument for easier monetary policy.
Only 29,000 jobs were added in September, substantially below expectations.
Yet bond yields remain elevated, energy prices are adding to inflation concerns, and the Federal Reserve is still debating whether monetary policy needs further tightening.
This creates one of the most important investment questions entering the new week:
What happens when economic growth begins weakening but inflation risk prevents central banks from comfortably reducing interest rates?
That tension could influence bonds, equities, currencies, commodities and digital assets throughout Q4.
EXECUTIVE SUMMARY
Global markets are entering a complicated phase.
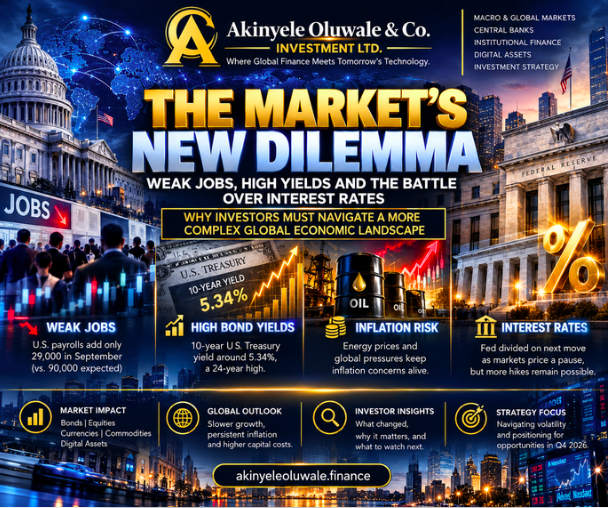
The September U.S. employment report showed the economy added just 29,000 jobs, compared with economists' expectations for approximately 90,000. The unemployment rate increased to 4.2%.
Ordinarily, weaker employment would increase expectations for lower interest rates.
But today's environment is different.
Inflation risks have not disappeared. Energy costs remain an important concern, while global government-bond markets have experienced a significant selloff. Reuters reported that major sovereign bond markets were heading into the end of September after one of their worst months in years.
The Federal Reserve itself is divided over the urgency of additional tightening.
Dallas Fed President Lorie Logan has argued that rates may need to rise by at least another 50 basis points, while other senior policymakers have indicated that the Fed can wait for additional evidence before making another move.
Markets are therefore confronting competing forces:
Slower employment → less pressure to raise rates
versus
Inflation + energy pressures → less room to lower rates
This is the macroeconomic tension investors need to understand.
WHY THIS MATTERS
Interest rates influence almost every major asset class.
The transmission mechanism can be simplified:
Inflation → Central Banks → Interest Rates → Bond Yields → Liquidity → Valuations → Capital Flows
When interest rates and bond yields rise, the cost of capital increases.
Governments pay more to borrow.
Companies face higher financing costs.
Mortgage and consumer-credit costs increase.
Investors can obtain higher yields from bonds and cash-like instruments.
That changes how much investors are willing to pay for riskier assets.
This is why today's bond-market movements matter far beyond fixed income.
They potentially influence:
Equities
Technology valuations
Real estate
Currencies
Commodities
Bitcoin and digital assets
Corporate borrowing
Government finances
The bond market is effectively changing the price of money throughout the financial system.
WHAT HAPPENED?
U.S. Employment Weakened Sharply
September nonfarm payrolls increased by only 29,000, considerably below the approximately 90,000 economists had expected.
August employment growth was also revised lower.
The unemployment rate rose to 4.2%.
That matters because employment is one of the Fed's most important economic indicators.
Weak employment normally reduces the need for tighter monetary policy.
Markets responded accordingly.
Reuters reported that expectations for the Fed to leave rates unchanged at its October meeting increased to around 80% following the employment report but Bond Yields Remained High
This is where the story becomes more interesting.
Despite weaker employment data, government bonds remained under pressure.
The U.S. 10-year Treasury yield recently reached around 5.34%, a 24-year high.
That means investors are not simply thinking about economic weakness.
They are also thinking about:
inflation,
energy prices,
government borrowing,
fiscal risk,
and the possibility that interest rates remain elevated for longer.
The Federal Reserve Is Sending Mixed Signals
The Fed raised its policy rate in September to 3.75%–4.00% and indicated that further tightening could still be required.
But the urgency of another increase is now being debated.
New York Fed President John Williams has suggested only one additional increase may be required this year and indicated there was no urgency for an immediate move.
Cleveland Fed President Beth Hammack similarly said policymakers still have time to evaluate incoming information before the October meeting.
Dallas Fed President Lorie Logan, however, has argued for at least another 50 basis points of tightening.
The disagreement reflects the difficult policy environment.
THE BIGGER PICTURE
The fundamental problem is that central banks may increasingly face two conflicting economic signals.
Signal One: Growth Is Slowing
Weakening employment suggests monetary tightening is beginning to affect economic activity.
Normally:
Slower economy → Lower inflation → Lower rates
But another force is interfering.
Signal Two: Inflation Risks Remain
Energy prices and geopolitical disruptions have increased inflation concerns.
This creates:
Higher energy → Higher production/transport costs → Inflation pressure → Higher-for-longer rates
Put the two together:
Slower Growth + Persistent Inflation = Policy Dilemma
Economists often associate this type of environment with stagflation risk weak growth occurring alongside persistent inflation.
That does not mean the global economy is necessarily entering full stagflation.
It means investors should watch whether the combination becomes more persistent.
MARKET IMPACT
Bonds
Bonds sit at the centre of today's macro story.
Higher yields reduce the present value of future cash flows and increase borrowing costs throughout the economy.
The global bond selloff has therefore become one of the most important market developments entering Q4.
Equities
Interestingly, U.S. stocks rose after the weak employment report.
The Nasdaq gained about 1.2%, with the broader market also advancing as investors reduced expectations of an October Fed increase.
That illustrates an unusual market dynamic:
Bad economic news can temporarily become good market news when it reduces expectations for higher interest rates.
But there is a limit.
If employment weakens too much, investors eventually stop celebrating lower-rate expectations and begin worrying about corporate earnings and recession risk.
The U.S. Dollar
The dollar has benefited recently from relatively high U.S. yields and weakness elsewhere.
It was on course for a fourth consecutive weekly gain against the euro on Friday, supported partly by elevated Treasury yields and concerns surrounding European government debt.
But currency strategists surveyed by Reuters generally expect much of the dollar's recent strength to fade over the coming year.
This creates another tension worth monitoring.
Oil and Inflation
Energy remains one of the biggest macroeconomic wildcards.
Higher oil prices can feed into:
transportation costs,
production costs,
consumer inflation,
and inflation expectations.
That means oil is no longer merely an energy-market story.
It is potentially an interest-rate story.
Bitcoin and Digital Assets
Digital assets should be analysed through the same liquidity framework.
Bitcoin and crypto markets can respond positively when investors expect easier monetary conditions and improved global liquidity.
But higher bond yields can create competition for speculative capital.
The important framework is therefore:
Rates → Liquidity → Risk Appetite → Capital Flows → Digital Assets
This does not determine Bitcoin's price mechanically.
But it remains an important macroeconomic transmission channel.
EDITORIAL PERSPECTIVE
At Akinyele Oluwale & Co. Investment Ltd., we believe investors should resist reducing today's environment to a simple question:
“Will the Fed hike or pause?”
That is too narrow.
The more important question is:
What is happening to the global cost of capital?
One Fed meeting can change expectations.
But the structural forces behind bond yields extend much further:
government borrowing,
inflation,
energy,
economic growth,
central-bank credibility,
AI-related capital investment,
and global demand for sovereign debt.
This is why we continue emphasizing the framework:
Inflation → Rates → Liquidity → Valuations → Capital Flows
Yesterday's Day 26 analysis showed how enormous AI infrastructure requirements are increasing demand for capital.
Today's analysis adds another layer:
That capital is becoming more expensive.
Put those two observations together and an important investment question emerges:
Which companies, governments and assets can still generate attractive returns when money is expensive?
That may be one of Q4 2026's defining questions.
WHAT TO WATCH NEXT
Investors should monitor several signals over the coming week:
1. Federal Reserve Minutes
Markets will examine the Fed's latest minutes for clues about how policymakers see inflation and the need for additional tightening. Reuters identifies the minutes as a key event for the coming week.
2. U.S. Treasury Yields
Watch whether the 10-year yield continues moving higher or whether buyers return at historically elevated yields.
3. Oil Prices
Another significant increase could strengthen inflation concerns.
4. Inflation Data
The critical question is whether inflation continues moderating despite energy pressures.
5. Employment
One weak payroll report is important.
A persistent weakening trend would be considerably more significant.
6. Corporate Earnings
Q3 earnings season will begin putting company fundamentals back at the centre of market attention. Reuters reports that analysts expect strong year-over-year profit growth, while investors will closely scrutinise AI capital expenditure.
7. The Dollar
Further dollar appreciation could tighten financial conditions globally.
8. Bitcoin and Risk Assets
Watch whether digital assets respond more strongly to weakening employment and potential monetary-policy relief—or to elevated bond yields and tighter financial conditions.
KEY TAKEAWAYS
U.S. employment is weakening. September payroll growth of only 29,000 was substantially below expectations.
An October Fed hike now appears less likely. Markets moved strongly toward expecting no change at the October meeting following the employment report.
But the inflation problem has not disappeared. Energy and broader price pressures continue complicating monetary policy.
Bond yields remain critical. High sovereign yields are raising the global cost of capital.
Stocks face competing forces. Lower expectations for immediate tightening can support valuations, but persistent high yields and weaker economic activity create risks.
Digital assets remain connected to global liquidity conditions.
And the central Day 27 lesson is:
Don't watch interest rates alone. Watch the cost of capital.
Because the cost of capital ultimately influences where money moves and what investors are willing to pay for assets.
ABOUT AKINYELE OLUWALE & CO. INVESTMENT LTD.
Akinyele Oluwale & Co. Investment Ltd* is a global finance and digital-economy intelligence platform focused on helping investors, professionals and decision-makers understand the forces reshaping modern markets.
Our intelligence covers:
Artificial Intelligence • Blockchain & Technology • Crypto & Digital Assets • Institutional Finance • Stablecoins & Payments • Tokenization & RWAs • Central Banks • Macro & Global Markets
Our analysis is built around three questions:
What changed?
Why does it matter?
What should investors watch next?
Our objective is to move beyond headlines and connect developments across macroeconomics, global markets, institutional finance and emerging technology.
Because information tells you what happened.
Intelligence helps you understand what it means.