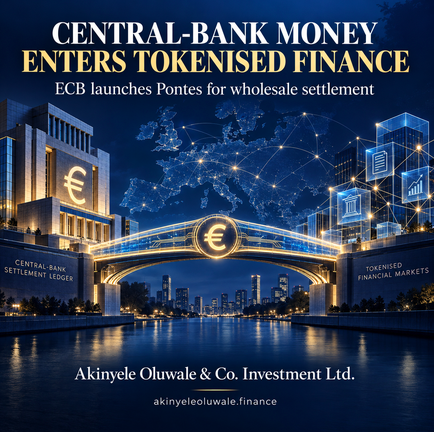
The ECB’s Pontes Launch Brings Central-Bank Money to Tokenised Financial Markets
Europe has introduced a settlement bridge connecting distributed-ledger transactions with trusted central-bank money moving tokenisation closer to functioning institutional infrastructure.
Published: 25 September 2026
Category: Tokenization & RWAs • Central Banks • Institutional Finance
By: Akinyele Oluwale & Co. Investment Ltd.
Executive Summary
The European Central Bank has launched Pontes, a new Eurosystem solution that connects wholesale financial transactions recorded on distributed-ledger technology platforms with central-bank money available through Europe’s existing TARGET settlement infrastructure.
Pontes addresses one of the most important obstacles facing institutional tokenisation: how the payment side of a tokenised transaction can be completed safely using trusted and legally recognised money.
This is not the launch of the proposed retail digital euro for consumers. Pontes is wholesale financial-market infrastructure intended primarily for banks, securities firms, market operators and other institutional participants.
Its launch signals that tokenisation is beginning to move beyond isolated experiments. However, its long-term significance will depend on transaction volumes, institutional adoption, platform interoperability, liquidity, cybersecurity and legal certainty.
Why This Matters
Creating a tokenised bond, fund or other financial asset is only one part of a transaction.
The buyer must also pay for the asset, and the seller must be confident that payment will be received when ownership changes.
In conventional financial markets, large institutional transactions frequently settle using central-bank money because it carries minimal credit and liquidity risk. As financial assets move onto distributed ledgers, institutions need a reliable mechanism for connecting those digital assets with equally trusted settlement money.
Pontes provides that connection.
A tokenised asset may be issued and transferred on a distributed ledger, while the corresponding payment is settled through established Eurosystem central-bank infrastructure.
This can help support delivery versus payment, under which the asset and money transfer together. It reduces the risk that one party delivers its side of a transaction while the other party fails to perform.
Without credible settlement arrangements, tokenisation may remain a collection of technical demonstrations. With trusted money, legal finality and institutional participation, it can develop into functioning financial-market infrastructure.
What Happened?
The Eurosystem launched Pontes on 21 September 2026 as part of its strategy to support the settlement of wholesale transactions involving distributed-ledger technology.
Pontes links eligible DLT market platforms with the Eurosystem’s TARGET services, which already provide settlement infrastructure for Europe’s financial system.
In simplified terms, the process works as follows:
1. A tokenised security is transferred through an eligible distributed-ledger platform.
2. A corresponding payment instruction is transmitted through the Pontes connection.
3. The cash obligation is settled using central-bank money through the Eurosystem’s infrastructure.
4. The transaction achieves institutional settlement finality.
The system combines innovation at the asset and transaction layer with established public-money infrastructure at the settlement layer.
Pontes follows extensive Eurosystem experimentation with distributed-ledger settlement. Between May and November 2024, the exploratory programme involved central banks, financial institutions and DLT market operators.
More than 200 transactions with a combined value of approximately €1.59 billion were processed. The activities included tokenised securities, primary-market issuance, secondary-market transactions, repurchase agreements and domestic and cross-border settlements.
The experiments helped the Eurosystem evaluate different methods of connecting transactions recorded on distributed ledgers with central-bank money. Pontes converts part of that exploratory work into operational infrastructure.
Pontes Is Not the Retail Digital Euro
Pontes must not be confused with the proposed retail digital euro.
It is not a consumer wallet, cryptocurrency or new payment card. Members of the public will not use Pontes to purchase goods or transfer money to friends.
The euro already exists digitally within the banking and central-bank system. Pontes allows central-bank money within existing Eurosystem infrastructure to settle eligible wholesale transactions recorded on distributed ledgers.
The proposed retail digital euro is a separate project intended to give individuals and businesses access to a public digital payment method for ordinary transactions.
The ECB aims to be technically prepared for a possible retail digital euro issuance in 2029, provided the required European legislation is adopted. A final issuance decision has not yet been made.
The Bigger Picture
Pontes forms part of a wider restructuring of financial-market infrastructure.
Banks, exchanges, asset managers, governments and technology companies are exploring how bonds, investment funds, deposits, collateral and other financial instruments can be represented as digital tokens.
Tokenisation may provide several advantages:
- Faster settlement;
- Automated corporate actions;
- Reduced reconciliation;
- Improved transaction transparency;
- Programmable ownership and payments;
- More efficient collateral management;
- Extended operating hours; and
- Potentially lower administrative costs.
However, tokenisation alone does not create a functioning market.
Institutional markets also require:
- Trusted settlement money;
- Legal recognition of ownership;
- Reliable custody;
- Identity and compliance systems;
- Cybersecurity;
- Interoperability;
- Active buyers and sellers; and
- Procedures for resolving failed transactions.
Pontes primarily addresses the settlement-money component.
It also demonstrates that the future of finance is likely to be hybrid.
Distributed ledgers may provide token issuance, digital ownership records and programmable transactions. Central banks and established financial institutions may continue providing trusted money, regulation, liquidity and legal finality.
The emerging model is therefore not necessarily blockchain replacing the existing financial system. It is blockchain being integrated into the financial infrastructure that institutions already trust.
Public Money and Private Digital Money
Pontes also reflects growing competition over the future of digital money.
Private institutions are developing:
- Stablecoins;
- Tokenised commercial-bank deposits;
- Deposit tokens;
- Programmable payment systems; and
- Blockchain-based treasury products.
Central banks want to ensure that public money remains central to the financial system as assets and transactions become increasingly digital.
Europe does not want its future tokenised capital markets to depend entirely on foreign-currency stablecoins or privately issued settlement instruments.
Pontes therefore has strategic as well as technological significance. It allows Europe to encourage tokenisation while preserving an important role for euro-denominated central-bank money.
Stablecoins, tokenised deposits and central-bank money may all coexist. Their roles, however, will differ.
Stablecoins may remain useful for digital commerce and cross-border transfers. Tokenised deposits may support programmable services within commercial banking. Central-bank money is likely to remain particularly important for final settlement between regulated financial institutions.
Market Impact
Pontes does not automatically create a liquid European tokenised-securities market. It does, however, remove an important infrastructure barrier.
Impact on banks and financial institutions
Banks can explore tokenised assets without depending entirely on privately issued settlement tokens.
This could improve institutional confidence and support the development of tokenised bonds, investment funds, collateral and repurchase agreements.
Banks may also need to invest further in:
- Digital custody;
- Compliance systems;
- DLT connectivity;
- Cybersecurity;
- Smart-contract controls; and
- Operational risk management.
Impact on asset issuers
Governments, companies and financial institutions may gain a more credible pathway for issuing tokenised securities.
However, the economic benefits must be demonstrated. Issuers will compare the costs of tokenisation with those of conventional issuance and settlement.
Tokenisation will scale only if it produces meaningful improvements in cost, speed, transparency, liquidity or access.
Impact on infrastructure providers
The development may create opportunities for companies providing:
- Tokenisation platforms;
- Institutional digital custody;
- Blockchain interoperability;
- Compliance technology;
- Identity verification;
- Smart-contract auditing;
- Cybersecurity; and
- Market-data services.
Not every company associated with tokenisation will become profitable. Investors must assess recurring revenue, regulatory positioning, technological resilience and the ability to achieve institutional adoption.
Impact on stablecoins and tokenised deposits
Pontes may increase competition among potential settlement assets.
Stablecoins and tokenised bank deposits may still offer advantages in specific markets. Central-bank settlement, however, provides a particularly strong foundation for systemically important institutional transactions.
The likely outcome is not one settlement instrument eliminating every alternative. Different forms of digital money may serve different users, markets and regulatory requirements.
Editorial Perspective
Pontes is important because it represents practical financial infrastructure rather than another speculative blockchain announcement.
Its launch supports the argument that tokenisation is gradually moving from experimentation toward institutional implementation.
However, the existence of a settlement bridge should not be mistaken for proof that tokenised markets have already achieved scale.
Technology can create a digital representation of an asset. It cannot automatically create liquidity, legal certainty, investor demand or commercially viable markets.
The critical test is whether Pontes can support repeatable transactions across different platforms without introducing excessive complexity, fragmentation or operational risk.
Europe’s approach is strategically measured. Rather than discarding functioning financial infrastructure, the Eurosystem is connecting new distributed-ledger platforms to existing central-bank settlement systems.
That approach may appear less revolutionary than building an entirely separate blockchain financial system. It may also be more credible.
Financial institutions are more likely to adopt tokenisation when innovation is connected to trusted money, established law and resilient market infrastructure.
The central conclusion is clear:
> Tokenisation becomes financial infrastructure when digital assets can settle safely in trusted money with legal finality, operational resilience and sufficient liquidity.
Pontes creates the bridge. The market must now demonstrate whether institutions will use it at scale.
What to Watch Next
The success of Pontes should be measured by adoption and execution rather than its launch announcement alone.
Investors and financial institutions should monitor:
1. Transaction value and volume
The number and value of live transactions will show whether institutions are moving from testing to regular commercial activity.
2. Participating institutions
Adoption by banks, asset managers, exchanges, central securities depositories and public-sector issuers will influence the system’s credibility and network effects.
3. Types of tokenised assets
Government bonds, corporate debt, investment funds, collateral and repurchase agreements may develop at different speeds.
4. Platform interoperability
Pontes must connect efficiently with different distributed ledgers without producing isolated systems or fragmented liquidity.
5. Legal certainty
Market participants require clear rules concerning digital ownership, custody, settlement finality, insolvency and failed transactions.
6. Operational resilience
Institutional infrastructure must withstand cyberattacks, system failures, network congestion and other operational disruptions.
7. Settlement availability
Extended or continuous settlement could become an important advantage if Pontes eventually supports institutional transactions beyond conventional market hours.
8. Market liquidity
A tokenised asset is not automatically liquid. The development of active buyers, sellers, market makers and financing mechanisms will be essential.
9. Cross-border connectivity
Tokenised markets will eventually require coordination between currencies, central banks, regulatory jurisdictions and settlement systems.
10. Development of Appia
The Eurosystem’s longer-term **Appia** initiative is expected to address the broader development of an integrated European tokenised-finance ecosystem.
Pontes is the immediate bridge. Appia represents the longer-term vision.
Key Takeaways
- The Eurosystem has launched Pontes to connect wholesale DLT transactions with central-bank settlement infrastructure.
- Pontes is not the proposed retail digital euro and is not intended for everyday consumer payments.
- The system addresses a critical institutional requirement: settling tokenised transactions in trusted central-bank money.
- Its launch moves European tokenisation closer to operational financial infrastructure.
- The future financial system is likely to be hybrid, combining distributed ledgers with established banking and central-bank systems.
- Pontes does not eliminate the need for legal certainty, interoperability, cybersecurity and market liquidity.
- Adoption, transaction volumes and institutional participation will determine its long-term significance.
- Investors should focus on companies providing useful infrastructure rather than treating every tokenisation-related announcement as an investment opportunity.
About Akinyele Oluwale & Co. Investment Ltd.
Akinyele Oluwale & Co. Investment Ltd. is a digital-finance intelligence and investment-analysis company focused on the forces reshaping global finance.
Our coverage includes digital assets, institutional crypto adoption, stablecoins and digital payments, tokenisation and real-world assets, artificial intelligence, blockchain technology, central-bank policy, macroeconomics and global markets.
We provide independent, evidence-based analysis designed to help investors, institutions and decision-makers understand what changed, why it matters and what to watch next.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow’s Technology.
Visit akinyeleoluwale.finance for institutional analysis of digital finance, emerging technology and global markets.