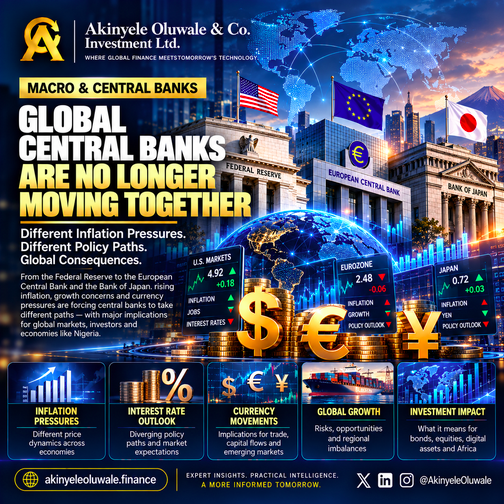
From Washington to Tokyo and Frankfurt, inflation, economic growth and currency pressures are forcing policymakers to make increasingly different decisions. The consequences could reshape global capital flows, borrowing costs and investment strategies.
Published: October 28, 2026 | Category: Central Banks | By: Akinyele Oluwale
For much of the past decade, global investors became accustomed to watching the world's major central banks move in broadly similar directions. When inflation surged, monetary authorities tightened financial conditions. When economic activity weakened, attention shifted towards possible interest-rate reductions.
That familiar pattern is becoming less reliable.
As October 2026 draws to a close, the Federal Reserve, European Central Bank and Bank of Japan face different combinations of inflation risks, growth pressures and financial-market expectations.
In the United States, investors are watching whether persistent inflation will keep interest rates elevated. In Europe, policymakers must weigh price stability against an uncertain growth environment. In Japan, currency weakness and domestic price pressures have created a different monetary-policy challenge.
Meanwhile, New Zealand's unexpected decision to maintain its policy rate at 2.75% illustrates how easily market expectations can be challenged.
These developments reveal an important reality: the global economy may be interconnected, but central banks do not necessarily face identical economic conditions.
For investors, this means monetary-policy analysis must go beyond asking whether global interest rates are rising or falling.
The more useful questions are: Which economy faces the greatest inflation pressure? Which central bank has room to change policy? How will differences in interest rates influence exchange rates, capital flows and asset valuations?
The next chapter of global monetary policy may be defined less by coordination and more by divergence.
Imagine three businesses operating in different countries.
The first is a manufacturing company in the United States that needs additional financing to expand production.
The second is a European exporter whose profitability depends partly on the exchange rate between the euro and the dollar.
The third is a Japanese company that imports raw materials priced in foreign currency.
All three businesses are affected by interest rates, but not in the same way.
The American manufacturer is concerned about borrowing costs. The European exporter is sensitive to currency competitiveness. The Japanese importer faces the possibility that a weaker yen will increase the domestic cost of imported materials.
Now imagine that their respective central banks make different policy decisions.
The Federal Reserve maintains relatively restrictive financial conditions. The European Central Bank adopts a more cautious approach because of weaker economic activity. The Bank of Japan signals concern about currency-driven inflation.
Those differences could influence business decisions even if none of the companies changes its underlying products or services.
This is why central-bank divergence matters.
Monetary policy affects not only how much money costs, but also where international capital may move, how currencies are valued and which businesses face the greatest financial pressure.
For emerging economies, including Nigeria, these international developments can influence foreign-exchange conditions, external borrowing costs and investor appetite for local assets.
The important lesson is simple: a central-bank decision made thousands of kilometres away can influence financial conditions in another economy, even when the underlying economic challenges are different.
Several developments during the final week of October have brought central-bank divergence into sharper focus.
Ahead of its October 28 monetary-policy announcement, financial markets broadly expected the Federal Reserve to leave its benchmark interest rate unchanged.
However, expectations of an unchanged rate did not remove uncertainty about the future direction of policy.
Investors were particularly interested in whether the Federal Reserve would continue emphasising inflation risks and whether its communication would suggest that restrictive financial conditions might remain necessary.
The distinction matters because financial markets often adjust before interest rates actually change.
A statement indicating greater concern about inflation could influence bond yields and currency markets even without an immediate rate increase.
The European Central Bank faces the challenge of maintaining price stability while monitoring economic activity across economies with different industrial structures, labour markets and fiscal conditions.
An interest-rate policy that appears suitable for one euro-area economy may create greater pressure in another.
The ECB must therefore consider economic conditions across the monetary union rather than responding to developments in a single country.
Its late-October policy deliberations are important because investors want to understand whether inflation risks or growth concerns will dominate future decisions.
Japan presents another important example.
Ahead of its October 29–30 policy meeting, the Bank of Japan was widely expected to maintain its policy rate at 1.25%.
However, market attention was also focused on whether policymakers would signal the possibility of further tightening.
A weaker yen can raise the local-currency cost of imported goods and energy. This can complicate inflation management even when domestic economic growth remains uncertain.
The Bank of Japan must therefore consider the interaction between wages, consumer prices, economic activity and exchange-rate developments.
The Reserve Bank of New Zealand maintained its policy rate at 2.75%, surprising investors who had anticipated an increase.
The New Zealand dollar weakened following the announcement.
This episode illustrates a fundamental principle of financial markets: prices respond not merely to economic events, but to the difference between actual outcomes and prior expectations.
A central bank can leave rates unchanged and still produce a significant market reaction.
To understand what is happening, we must distinguish between two important concepts: global economic integration and domestic monetary-policy responsibility.
Global economic integration means that countries are connected through trade, investment, technology, banking and financial markets.
Domestic monetary-policy responsibility means that each central bank must make decisions based primarily on its legal mandate and the economic conditions within its jurisdiction.
These two realities can create tension.
For example, an increase in global energy prices may affect several countries simultaneously. But the inflationary consequences will differ depending on their energy dependence, exchange rates, government policies and economic structures.
An oil-importing economy may experience rising production and transport costs. An oil-exporting economy may receive additional foreign-exchange revenue, although its consumers and businesses could still face higher domestic energy costs.
Similarly, a stronger US dollar may improve the international purchasing power of American consumers while increasing the local-currency cost of dollar-denominated imports or debt elsewhere.
The same global development can therefore create different policy challenges.
Another important factor is the time lag associated with monetary policy.
Central banks can change their policy rates quickly, but the economic consequences take time to emerge.
Existing loan contracts may not immediately reprice. Companies may continue investment projects approved months earlier. Households may adjust spending gradually.
As a result, policymakers must make decisions using both current information and forecasts about future economic conditions.
This introduces uncertainty.
If a central bank waits until inflation has completely disappeared before changing policy, it may maintain restrictive conditions longer than necessary.
If it eases too early, inflationary pressure may persist.
There is no perfect formula that eliminates these risks.
Effective monetary policy therefore depends on credible institutions, reliable economic information, sound judgement and clear communication.
Central-bank divergence can influence several important areas of the global financial system.
Different interest-rate expectations can change the relative attractiveness of currencies.
If investors expect interest rates to remain higher in one economy than another, assets denominated in the higher-yielding currency may attract additional attention.
However, interest-rate differences are not the only factor affecting exchange rates. Inflation, growth, financial stability and investor confidence also matter.
Institutional investors regularly compare investment opportunities across countries.
Government bonds, corporate debt, equities and other financial assets compete for international capital.
When expected returns or perceived risks change, investors may adjust their allocations.
These adjustments can influence financial conditions in emerging markets, particularly where foreign portfolio investment is an important source of capital.
Governments issue debt to finance expenditure and refinance existing obligations.
When global borrowing costs rise, governments may face higher interest expenses on newly issued or refinanced debt.
This can create additional pressure on public budgets, particularly in countries with significant debt-servicing commitments.
Businesses often evaluate expansion projects using the weighted average cost of capital.
When borrowing costs increase, the minimum return required to justify a project may also rise.
A project that appeared financially attractive under lower interest rates may become less attractive when financing becomes more expensive.
This does not automatically mean the project should be abandoned. It means management must reassess its expected cash flows, risks and financing arrangements.
Equity valuations are influenced partly by expectations about future earnings and the rates used to discount those earnings.
Digital assets can also respond to changes in financial-market liquidity and investor risk appetite.
However, neither equities nor cryptocurrencies move according to a guaranteed interest-rate formula.
Their performance also depends on earnings, adoption, regulation, market structure and asset-specific developments.
Investors should therefore avoid assuming that a particular central-bank decision must produce a predetermined market outcome.
One of the most common mistakes in financial analysis is to treat the global economy as though it were a single country operating under one monetary-policy framework.
It is not.
The United States, euro area, Japan and emerging economies operate under different economic structures, institutional arrangements and policy constraints.
A decision that appears appropriate in Washington may be unsuitable in Tokyo.
A policy response designed for the euro area may not address the challenges facing an African economy.
This is why serious financial intelligence must examine the reasons behind policy decisions rather than merely reporting whether interest rates increased or decreased.
For business leaders, the implications are practical.
A company should not develop its financing strategy around the assumption that interest rates will soon decline.
It should examine how its cash flows would perform under several possible scenarios.
What happens if borrowing costs remain elevated?
What happens if the local currency weakens?
What happens if customers reduce spending?
What happens if imported raw materials become more expensive?
These questions are especially important for businesses with significant foreign-currency obligations or exposure to international supply chains.
For investors, discipline requires understanding the risks associated with changing monetary conditions.
The objective should not be to predict every central-bank announcement correctly.
It should be to understand how different outcomes could affect the assets, businesses and economies being analysed.
The most valuable financial analysis is not the loudest prediction. It is the explanation that helps decision-makers understand uncertainty before that uncertainty becomes a financial problem.
Several developments deserve attention as October gives way to November.
First, the Federal Reserve's official communication. Investors should examine its assessment of inflation, employment, economic growth and the future direction of monetary policy.
Second, the European Central Bank's policy guidance. The balance between inflation risks and economic activity will help determine how markets interpret the euro-area outlook.
Third, the Bank of Japan's policy decision. Particular attention should be paid to comments about wages, underlying inflation and the effects of currency movements.
Fourth, global bond yields. Changes in government borrowing costs may reveal how investors are reassessing inflation and interest-rate expectations.
Fifth, exchange-rate developments. The dollar, euro and yen remain important reference points for international trade and financial markets.
Sixth, energy prices. Sustained changes in energy costs could influence inflation expectations and complicate monetary-policy decisions.
Finally, emerging-market responses. Investors should assess how global developments interact with domestic inflation, exchange-rate conditions, fiscal policy and economic growth.
For Nigeria, these issues are particularly relevant to businesses that import goods, service foreign-currency debt or depend on international financing.
The direction of global interest rates matters, but the domestic policy environment remains equally important.
Global central banks face increasingly different economic challenges, even though their financial systems remain interconnected.
The Federal Reserve, European Central Bank and Bank of Japan must balance inflation and growth under different domestic conditions.
An unchanged policy rate can still move financial markets when the decision differs from expectations.
Differences in monetary-policy outlooks can influence currencies, capital flows, borrowing costs and asset valuations.
Emerging economies must consider both international financial conditions and domestic economic fundamentals.
Businesses should evaluate investment and financing decisions under multiple interest-rate and exchange-rate scenarios.
Investors should distinguish confirmed central-bank decisions from forecasts, expectations and market interpretations.
Akinyele Oluwale & Co. Investment Ltd. is a financial intelligence platform focused on global finance, macroeconomics, central banking, institutional investment, digital assets and emerging financial technologies.
Our mission is to help readers understand important economic developments through evidence-based analysis, clear explanations and practical financial education.
We believe financial information becomes most valuable when readers can connect major global developments with the decisions facing businesses, investors and policymakers.
The world is entering a period in which central banks may increasingly follow different policy paths.
That divergence should not automatically be interpreted as a sign of global economic instability. It reflects the reality that economies experience inflation, growth and financial pressures differently.
However, it does create additional complexity for businesses and investors operating across borders.
Interest rates, exchange rates, bond yields and capital flows will remain important indicators of how monetary-policy expectations are evolving.
The responsibility of serious financial analysis is to interpret these developments carefully, identify the relevant risks and avoid presenting uncertain outcomes as established facts.
In a changing global economy, understanding why central banks make different decisions may be more valuable than attempting to predict which institution will move first.
Observe the change. Understand the implications. Position with discipline.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow’s Technology.