UK Explores Tokenised Gold as Blockchain Moves Deeper Into Traditional Markets
Published: September 15, 2026
Category: Tokenization & RWAs / Institutional Finance
By: Akinyele Oluwale
Executive Summary
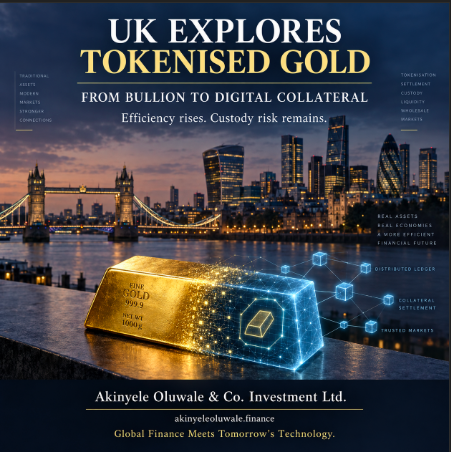
The United Kingdom’s Financial Conduct Authority is examining whether physical gold represented through blockchain-based tokens could improve trading, settlement, custody and collateral movement in wholesale financial markets.
The regulator is considering guidance or a bespoke regime for tokenised gold. However, no exemption or new regulatory framework has been approved.
Tokenisation may make gold easier to divide, transfer and pledge. It does not eliminate the fundamental risks surrounding custody, ownership, auditing, redemption and issuer insolvency.
Background
Tokenised gold is a digital representation of an ownership claim over physical bullion. Each token should correspond to a defined quantity of gold held by an issuer or custodian.
The FCA’s call for input follows a broader consultation conducted with the Bank of England on tokenisation in wholesale markets. Industry respondents identified post-trade operations particularly the movement of collateral as one of the strongest potential applications.
The regulator is now examining whether uncertainty under collective-investment-scheme and alternative-investment-fund rules is discouraging tokenised-gold development in Britain.
Responses to the consultation close on October 23, 2026. The feedback may lead to regulatory guidance or consideration of a dedicated framework. FCA
Why It Matters
London is one of the world’s most important centres for wholesale gold trading. Tokenisation could help modernise this market while strengthening the UK’s position in digital financial infrastructure.
Gold currently moves through complex networks of vaults, custodians, clearing members and settlement institutions. A well-designed token could accelerate ownership transfers, enable smaller denominations and allow gold to move more efficiently as collateral.
The broader significance is that blockchain is progressing beyond cryptocurrency speculation towards the infrastructure supporting established financial assets.
Stakeholders: Winners and Losers
Potential winners include bullion banks, regulated custodians, tokenisation platforms, institutional investors and financial-market infrastructure providers. Investors could benefit from improved accessibility and faster settlement.
Potential losers may include inefficient intermediaries whose revenues depend on slow or fragmented processes. Unregulated issuers could also struggle if the UK imposes strict custody, disclosure and redemption requirements.
Physical vaults and professional custodians will not disappear. Tokenised gold still requires someone to hold, insure, verify and protect the underlying metal.
Short-Term Impact
The consultation could encourage banks, fintech firms and bullion-market participants to develop pilot projects. It may also increase interest in existing gold-backed tokens.
However, investors should not interpret the consultation as regulatory approval of every tokenised-gold product. Each issuer’s structure and legal protections remain decisive.
Long-Term Impact
If Britain establishes a credible framework, tokenised gold could become usable across regulated trading, collateral and settlement systems.
This could eventually connect gold with tokenised bonds, deposits, funds and central-bank settlement infrastructure. The important transformation would not simply be gold moving onto blockchain, but traditionally separate assets becoming interoperable within digital markets.
Editorial Perspective
Tokenisation can improve the machinery of ownership, but it cannot strengthen a weak ownership claim.
A token is only as credible as the gold reserves, custodian, audit process, redemption mechanism and legal documentation behind it. If investors cannot confirm where the bullion is held, who owns it during insolvency and how redemption works, the token should not be treated as equivalent to physical gold.
The blockchain may prove that a token exists. It does not independently prove that the promised gold exists.
What to Watch Next
* Responses submitted before October 23.
* Whether the FCA proposes guidance or a bespoke regime.
* Treatment under CIS and AIF rules.
* Custody, insurance and reserve-audit standards.
* Legal ownership during issuer or custodian insolvency.
* Whether tokenised gold becomes eligible wholesale collateral.
* The joint FCA Bank of England tokenisation roadmap expected later in 2026.
Notes
The FCA has requested industry views; it has not approved a final tokenised-gold regime. Sources: FCA tokenised-gold consultation, FCA wholesale-tokenisation statement and Reuters.
Akinyele Oluwale & Co. Investment Ltd.
Global Finance Meets Tomorrow’s Technology.akinyeleoluwale.finance