Published: October 25, 2026 | Category: Institutional Finance | By: Akinyele Oluwale
Related Categories: Crypto & Digital Assets • Blockchain & Technology • Stablecoins & Payments
There were two institutional crypto stories this week. If you watched only Bitcoin's price and ETF flows, you saw nervousness. If you watched what banks and financial institutions were building, you saw something very different.
That distinction matters.
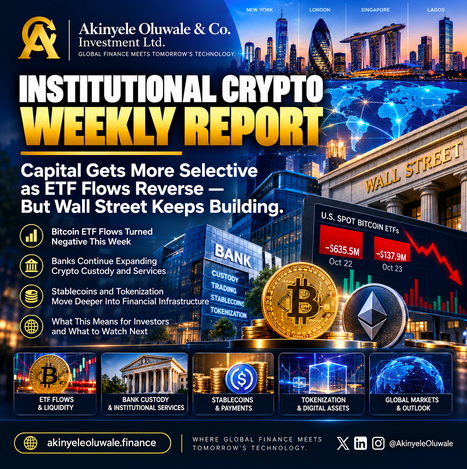
U.S. spot Bitcoin ETFs suffered approximately $635.5 million in net outflows on October 22, followed by another $137.9 million on October 23.
BlackRock's IBIT, which has been an important source of institutional Bitcoin demand, participated in the reversal.
At first glance, that could be interpreted as evidence that institutional enthusiasm for Bitcoin is weakening but that conclusion would be too simple because while capital was moving out of some investment products, institutional infrastructure continued moving forward.
Major financial institutions are still developing custody, trading, stablecoin, tokenization and digital-asset services.
This creates one of the most important distinctions investors need to understand about institutional crypto:
Institutional adoption and institutional buying are not the same thing.
Institutions can reduce exposure today while simultaneously investing in infrastructure they expect to use for years.
That is the central lesson from this week.
The institutional crypto market is entering a more demanding phase.
The early institutional-adoption story was relatively easy to understand.
Bitcoin ETFs launched.
Large asset managers entered.
Banks began discussing custody.
Corporate treasuries accumulated Bitcoin.
Institutional access expanded but the market is becoming more complicated.
ETF investors now have the infrastructure to move capital both into and out of Bitcoin efficiently.
Banks are no longer simply debating whether digital assets belong in finance; some are building services around custody, trading, stablecoins, tokenized deposits and digital securities.
Meanwhile, macroeconomic conditions continue to influence risk appetite.
This week's institutional crypto story can therefore be summarized through five signals:
ETF FLOWS → LIQUIDITY → MACRO CONDITIONS → INFRASTRUCTURE → INSTITUTIONAL INTEGRATION
The key message is straightforward:
Institutional crypto is becoming more established—but institutional capital is becoming more selective.
That is not necessarily a contradiction. It may be a sign of market maturation.
There is a common misunderstanding about institutional adoption.
People sometimes assume that if institutions believe in digital assets, institutional capital should continuously flow into Bitcoin.
Financial markets do not work that way.
Professional investors constantly rebalance.
They respond to:
Valuation
Interest rates
Liquidity
Risk
Portfolio exposure
Macroeconomic conditions
Client redemptions
Investment mandates
An institution can believe that Bitcoin has a long-term role in financial markets and still reduce its exposure this week.
An asset manager can launch a Bitcoin product without believing Bitcoin should rise every month.
A bank can build crypto custody infrastructure without taking a directional bet on Bitcoin's price.
That distinction is crucial.
Think about gold.
Banks provide gold trading, custody and investment products.
That does not mean they expect gold prices to rise every day.
The same principle increasingly applies to digital assets.
The institutionalisation of crypto means financial institutions are developing systems that allow clients to:
Hold
Trade
Transfer
Settle
Custody
Tokenize
Manage risk
That infrastructure can remain valuable regardless of what Bitcoin does next week.
ETF flows provided the week's most visible institutional signal.
Earlier in the week, demand was strong.
BlackRock's IBIT recorded a substantial inflow on October 19, while broader ETF demand helped support Bitcoin.
But the picture changed quickly.
On October 22, U.S. spot Bitcoin ETFs recorded approximately $635.5 million in net outflows.
BlackRock's IBIT accounted for roughly $254 million.
Fidelity's FBTC lost approximately $217.5 million.
ARKB recorded about $109.4 million in outflows.
Then came October 23.
The ETFs recorded another approximately $137.9 million in net outflows, with IBIT losing around $110.3 million.
Two consecutive sessions therefore produced approximately:
$773 million in combined net outflows.
That deserves attention.
But it needs context.
ETF flows can change quickly.
A large one-day inflow does not prove permanent institutional conviction.
Likewise, a large one-day outflow does not prove institutional abandonment.
The better question is:
Does the trend persist?
That is what investors should watch.
The more interesting development is where Bitcoin's marginal demand is coming from. Institutional market commentary this week highlighted an important shift.
Earlier in 2026, corporate treasury purchases were a major source of Bitcoin demand.
More recently, ETFs have played a much larger role.
Since August, U.S. spot Bitcoin ETFs have absorbed billions of dollars more than corporate treasury buyers.
That means Bitcoin's market structure is increasingly connected to traditional investment channels.
This is important for two reasons.
First, ETFs can bring significant institutional capital into Bitcoin.
Second, ETFs can also allow that capital to leave efficiently.
This changes Bitcoin's liquidity structure.
Institutionalisation does not eliminate volatility.
In some circumstances, it can transmit portfolio decisions from traditional financial markets into crypto more efficiently.
Consider the chain:
Macro Conditions → Institutional Risk Appetite → ETF Allocation → Bitcoin Liquidity → Price Discovery
Bitcoin therefore cannot be analysed purely as an isolated crypto asset anymore.
Interest rates matter.
Bond yields matter.
Dollar liquidity matters.
Portfolio positioning matters.
Institutional flows matter.
That is a major evolution.
Bitcoin spent the latter part of the week around the low-$80,000 region but the price itself is not the most interesting number.
The bigger question is whether institutional demand remains strong enough to absorb selling pressure.
Recent institutional research has identified roughly the $80,000–$82,000 region as particularly important because ETF investor cost bases and technical market levels have converged around that area.
This does not mean Bitcoin must hold a particular price.
Markets do not obey neat formulas.
But it does mean institutional flows deserve close attention.
If sustained ETF inflows return, they could provide additional liquidity.
If sustained outflows continue, one important source of marginal demand becomes weaker.
The lesson:
Watch the flow of capital not merely the price of the asset.
Ethereum's institutional story remains different.
Bitcoin's institutional narrative is increasingly connected to:
Store of value → Portfolio allocation → ETFs → Institutional liquidity
Ethereum's case extends more directly into:
Smart contracts → Tokenization → Stablecoins → Digital securities → Settlement infrastructure
That means evaluating Ethereum purely through short-term price movements misses part of the institutional thesis.
The longer-term question is whether public blockchain infrastructure captures meaningful economic activity from tokenized finance.
Stablecoins remain one of the most practical bridges between traditional finance and blockchain networks.
Their institutional importance is increasingly connected to:
Payments
Settlement
Treasury management
Cross-border transactions
Tokenized markets
This is why stablecoins should not be viewed only as instruments used by crypto traders.
The larger opportunity is potentially the infrastructure underneath digital money.
If regulated stablecoins become embedded in institutional payment and settlement systems, their importance could extend far beyond cryptocurrency exchanges.
At Akinyele Oluwale & Co. Investment Ltd., we believe this week's events reveal something important about where institutional crypto is heading.
The market is becoming less ideological.
That is healthy.
The old debate was:
“Will institutions adopt crypto?”
The emerging debate is more sophisticated:
Which digital assets?
Through which structures?
At what valuation?
Under what regulation?
Using which custody arrangements?
For what economic purpose?
At what level of portfolio exposure?
Those are institutional questions.
And they are very different from simply asking:
“Will Bitcoin go up?”
This week illustrates the difference perfectly.
Bitcoin ETF investors withdrew significant capital.
Yet major banks continued developing digital-asset infrastructure.
Both can happen simultaneously.
Why?
Because one is an allocation decision.
The other is an infrastructure decision.
Allocation decisions can change daily.
Infrastructure decisions are usually made with much longer time horizons.
This gives us a useful framework:
They are connected but they are not identical.
That distinction will become increasingly important as institutional crypto matures.
This is the immediate indicator.
One or two days of outflows should not be interpreted in isolation.
Watch whether outflows continue across several sessions.
Persistence matters more than headlines.
IBIT has become particularly important because of its size and its contribution to recent Bitcoin ETF demand.
Watch whether capital returns after the latest redemptions.
Institutional crypto does not exist outside the global economy.
Inflation expectations, interest rates, bond yields and liquidity conditions influence investors' willingness to hold volatile assets.
Crypto investors increasingly need to understand macroeconomics.
Deutsche Bank's planned institutional crypto custody rollout is one development worth monitoring.
The broader question is whether more global banks move from experimentation toward live client services.
Custody matters because institutional capital requires:
Security
Governance
Compliance
Reporting
Operational resilience
before it can participate at scale.
Watch whether banks treat stablecoins as competitors—or integrate similar blockchain-based settlement mechanisms into their own infrastructure.
The line between:
Stablecoins
Tokenized deposits
Central-bank money
Tokenized securities
may become one of the most important areas of financial innovation over the coming years.
Tokenization continues to move from concept toward financial infrastructure.
The important question is no longer simply whether an asset can be tokenized.
Almost anything can.
The better questions are:
Does tokenization reduce cost?
Does it improve settlement?
Does it increase liquidity?
Does it create useful programmability?
Does it operate within credible legal and regulatory frameworks?
Technology without economic utility will not produce institutional adoption at scale.
This week's institutional crypto developments leave us with seven important conclusions.
Institutions rebalance.
Outflows are part of functioning markets.
Watch trends rather than isolated daily numbers.
ETFs have become increasingly important relative to corporate treasury purchases.
Interest rates, liquidity and risk appetite increasingly matter.
Custody, trading, stablecoins, tokenized deposits and digital securities are gradually becoming part of institutional financial strategy.
Daily prices change quickly.
Financial infrastructure develops slowly.
Investors should understand both.
Capital will increasingly distinguish between:
Assets with liquidity
Assets with utility
Assets with credible infrastructure
Assets with institutional-grade custody
Assets with regulatory pathways
and everything else.
Our weekly framework is therefore:
And the principle underneath it:
Institutional adoption should be measured not only by how much capital enters crypto—but by how deeply digital assets become integrated into financial infrastructure.
Akinyele Oluwale & Co. Investment Ltd. provides financial intelligence and investment education focused on the intersection of global finance, institutional capital, markets and emerging technology.
Our institutional crypto coverage follows a simple philosophy.
We do not measure progress solely by price.
Bitcoin rising does not automatically mean institutional adoption is accelerating.
Bitcoin falling does not automatically mean institutional adoption is failing.
Instead, we monitor the deeper indicators:
Capital flows
Custody
Liquidity
Regulation
Bank participation
Asset management
Stablecoins
Tokenization
Settlement infrastructure
Institutional integration
These signals tell us more about the evolution of the financial system than any single day's market movement and this week provided an excellent example.
ETF flows turned sharply negative toward the end of the week.
That matters.
It should not be dismissed but it should not be exaggerated either.
At the same time, banks and financial institutions continued positioning themselves for a world in which digital assets, tokenized securities and blockchain-based settlement play a larger role.
That matters too.
The professional approach is to hold both facts simultaneously.
No hype.
No panic.
No assumption that every institutional announcement guarantees adoption and no assumption that every ETF outflow signals the end of institutional interest.
Instead:
Observe the capital.
Study the infrastructure.
Follow the regulation.
Measure real adoption.
Separate price from progress.
That is how institutional crypto should be analysed.
The next stage will not simply be about whether institutions enter digital assets.
Increasingly, it will be about:
which institutions,
through which infrastructure,
using which assets,
under which regulatory framework,
and for what economic purpose.
That is a much more serious conversation and it is evidence that institutional crypto itself is becoming a much more serious market.
Observe the change. Understand the implications. Position with discipline.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow's Technology.
akinyeleoluwale.finance
This publication is for educational and informational purposes and does not constitute individualized investment, financial, legal or tax advice.